Aarvion
A welder at work on a factory floor

Risk OS · Commercial Credit

Every commercial loan,
request to repayment.

New facilities, increases, renewals, drawdowns and amendments, across working capital, term loans, equipment, commercial real estate, construction and letters of credit.

Book a demo

One loan, one week, start to finish.

  1. Monday, 8:12 am

    A request comes in.

    Meridian Packaging wants a $750k increase on its revolver. The relationship manager writes one sentence and points to the client's folder. Aarvion builds the application and lists what's missing.
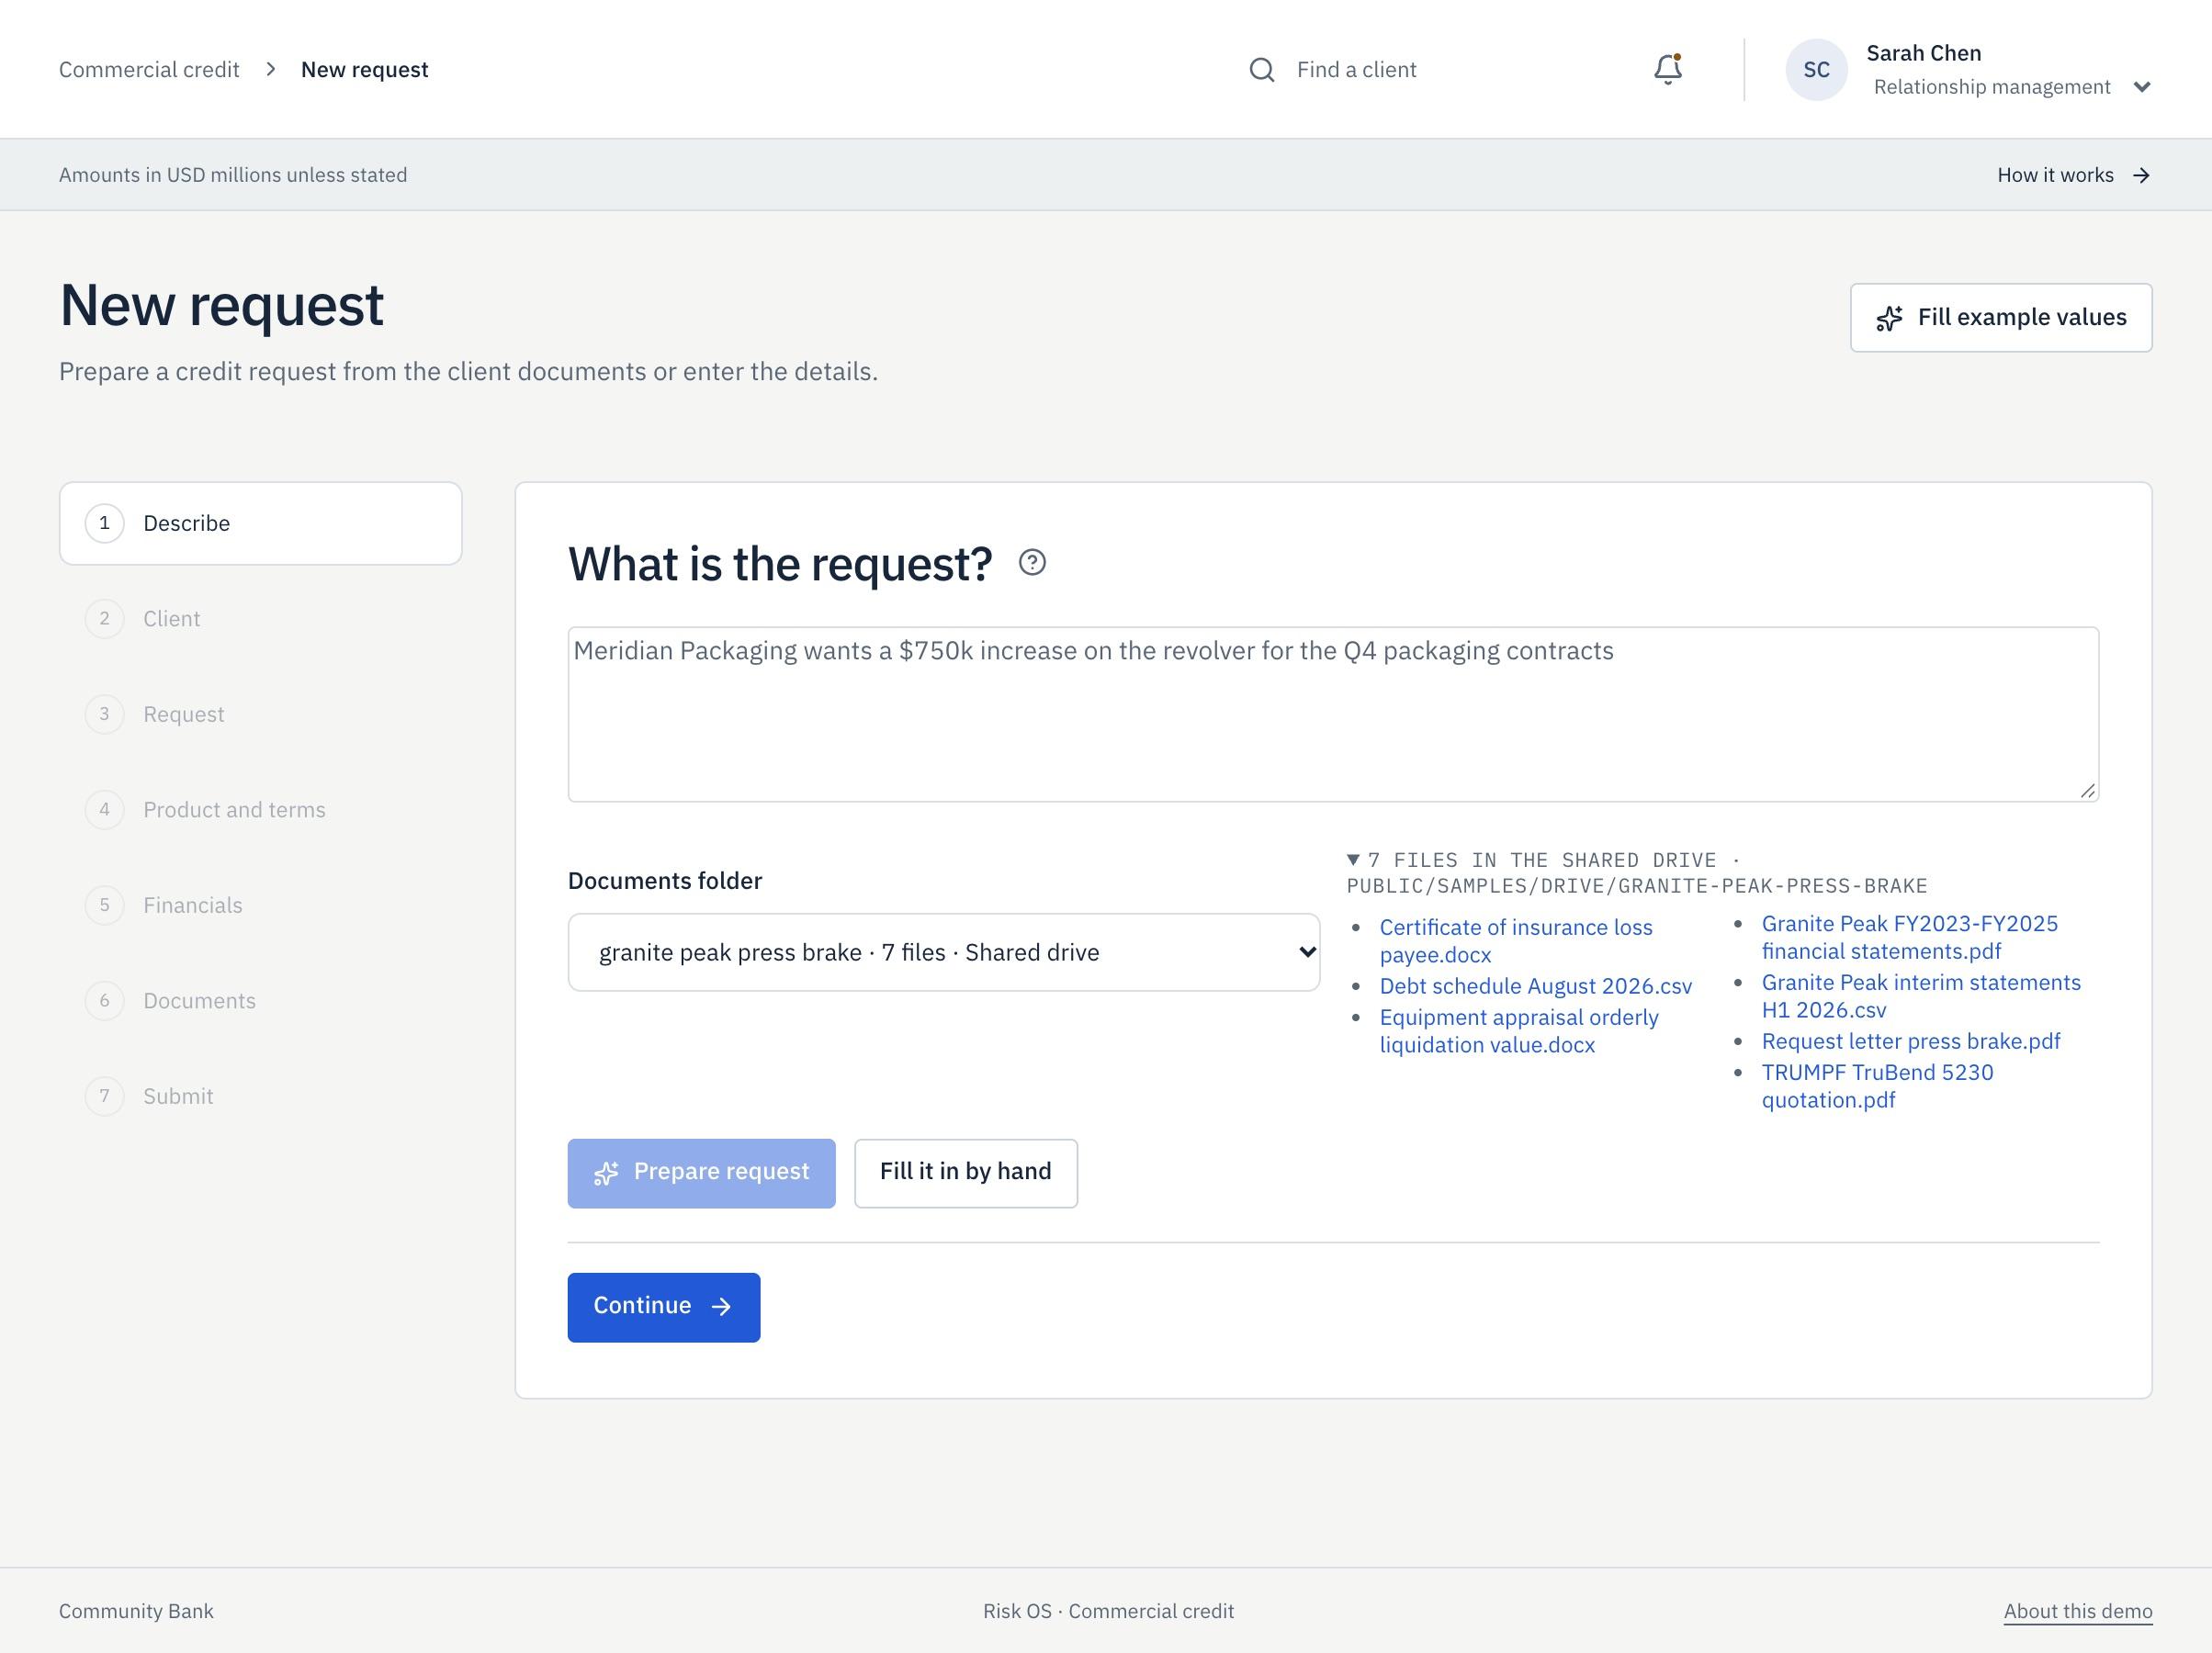
    New credit request assembled from a folder of client documents
  2. Monday, 11:30 am

    The numbers are spread.

    Three years of statements are spread with page references. Your policy tests run, the debt schedule is built, and an analyst confirms the figures.
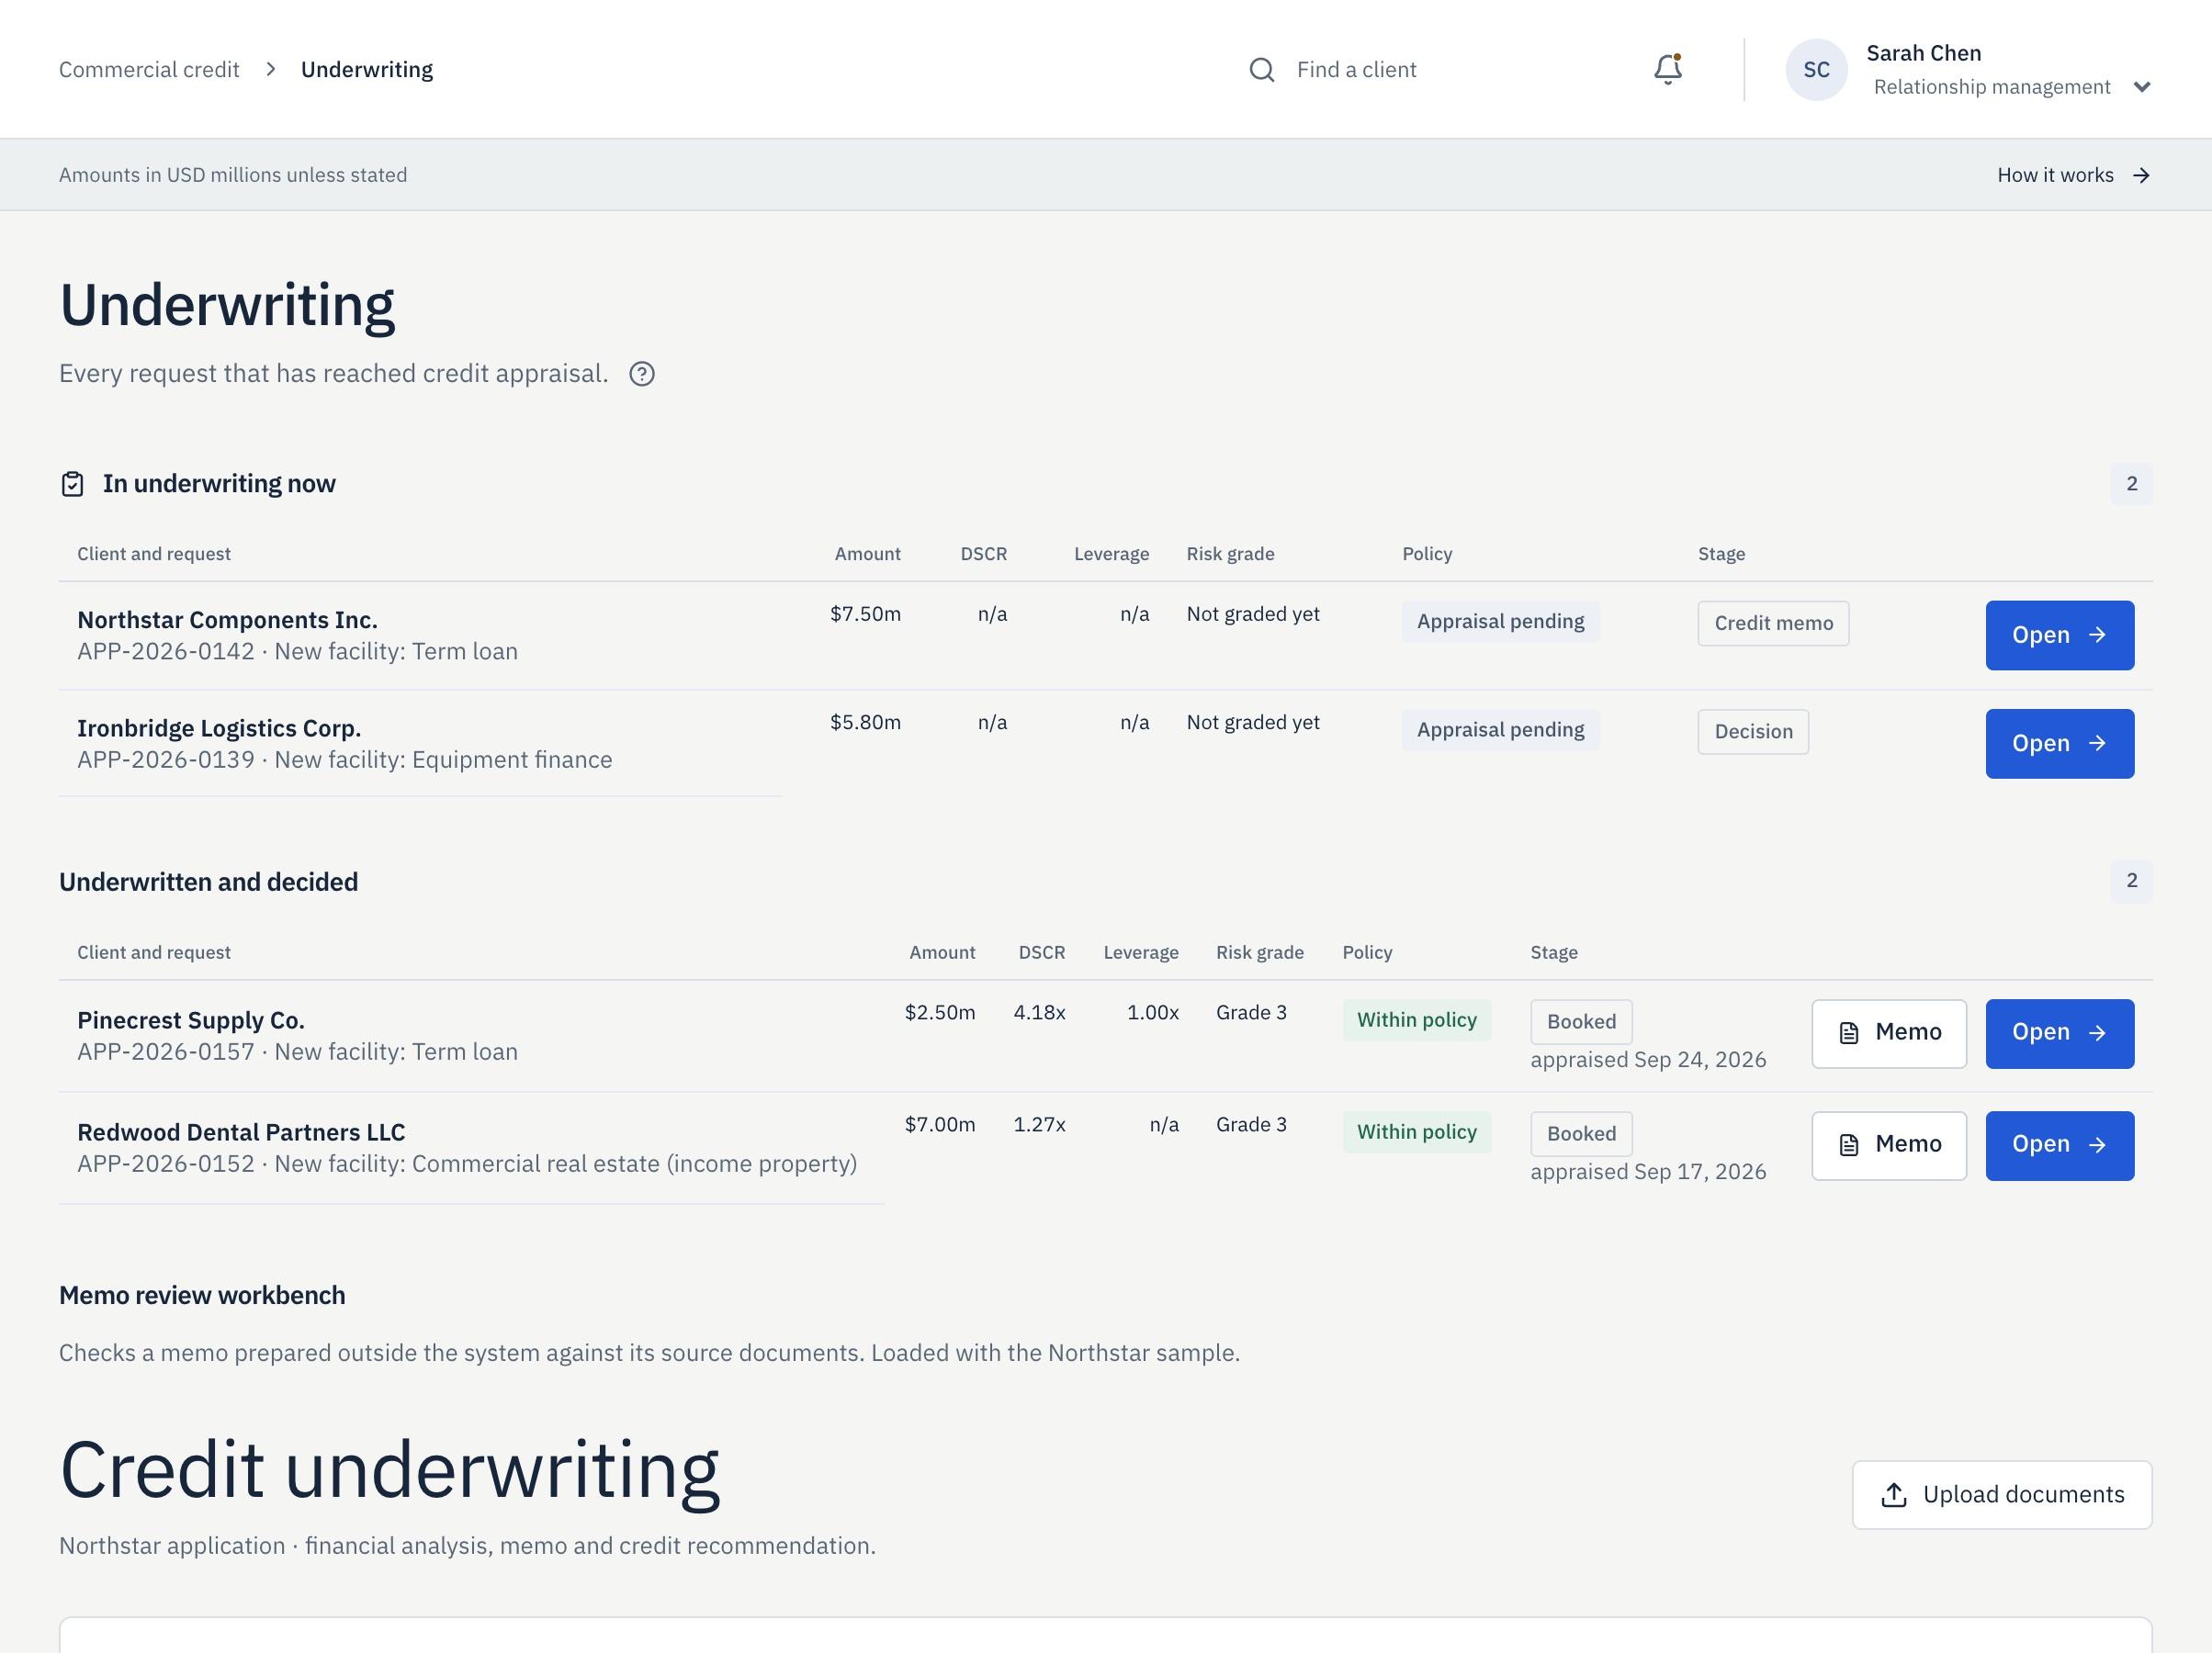
    Underwriting list with policy status and risk grade for each request
  3. Tuesday

    The memo is written.

    A full credit memo and committee pack, drafted from the confirmed spread and the source documents. Your credit officer edits it, not starts it.
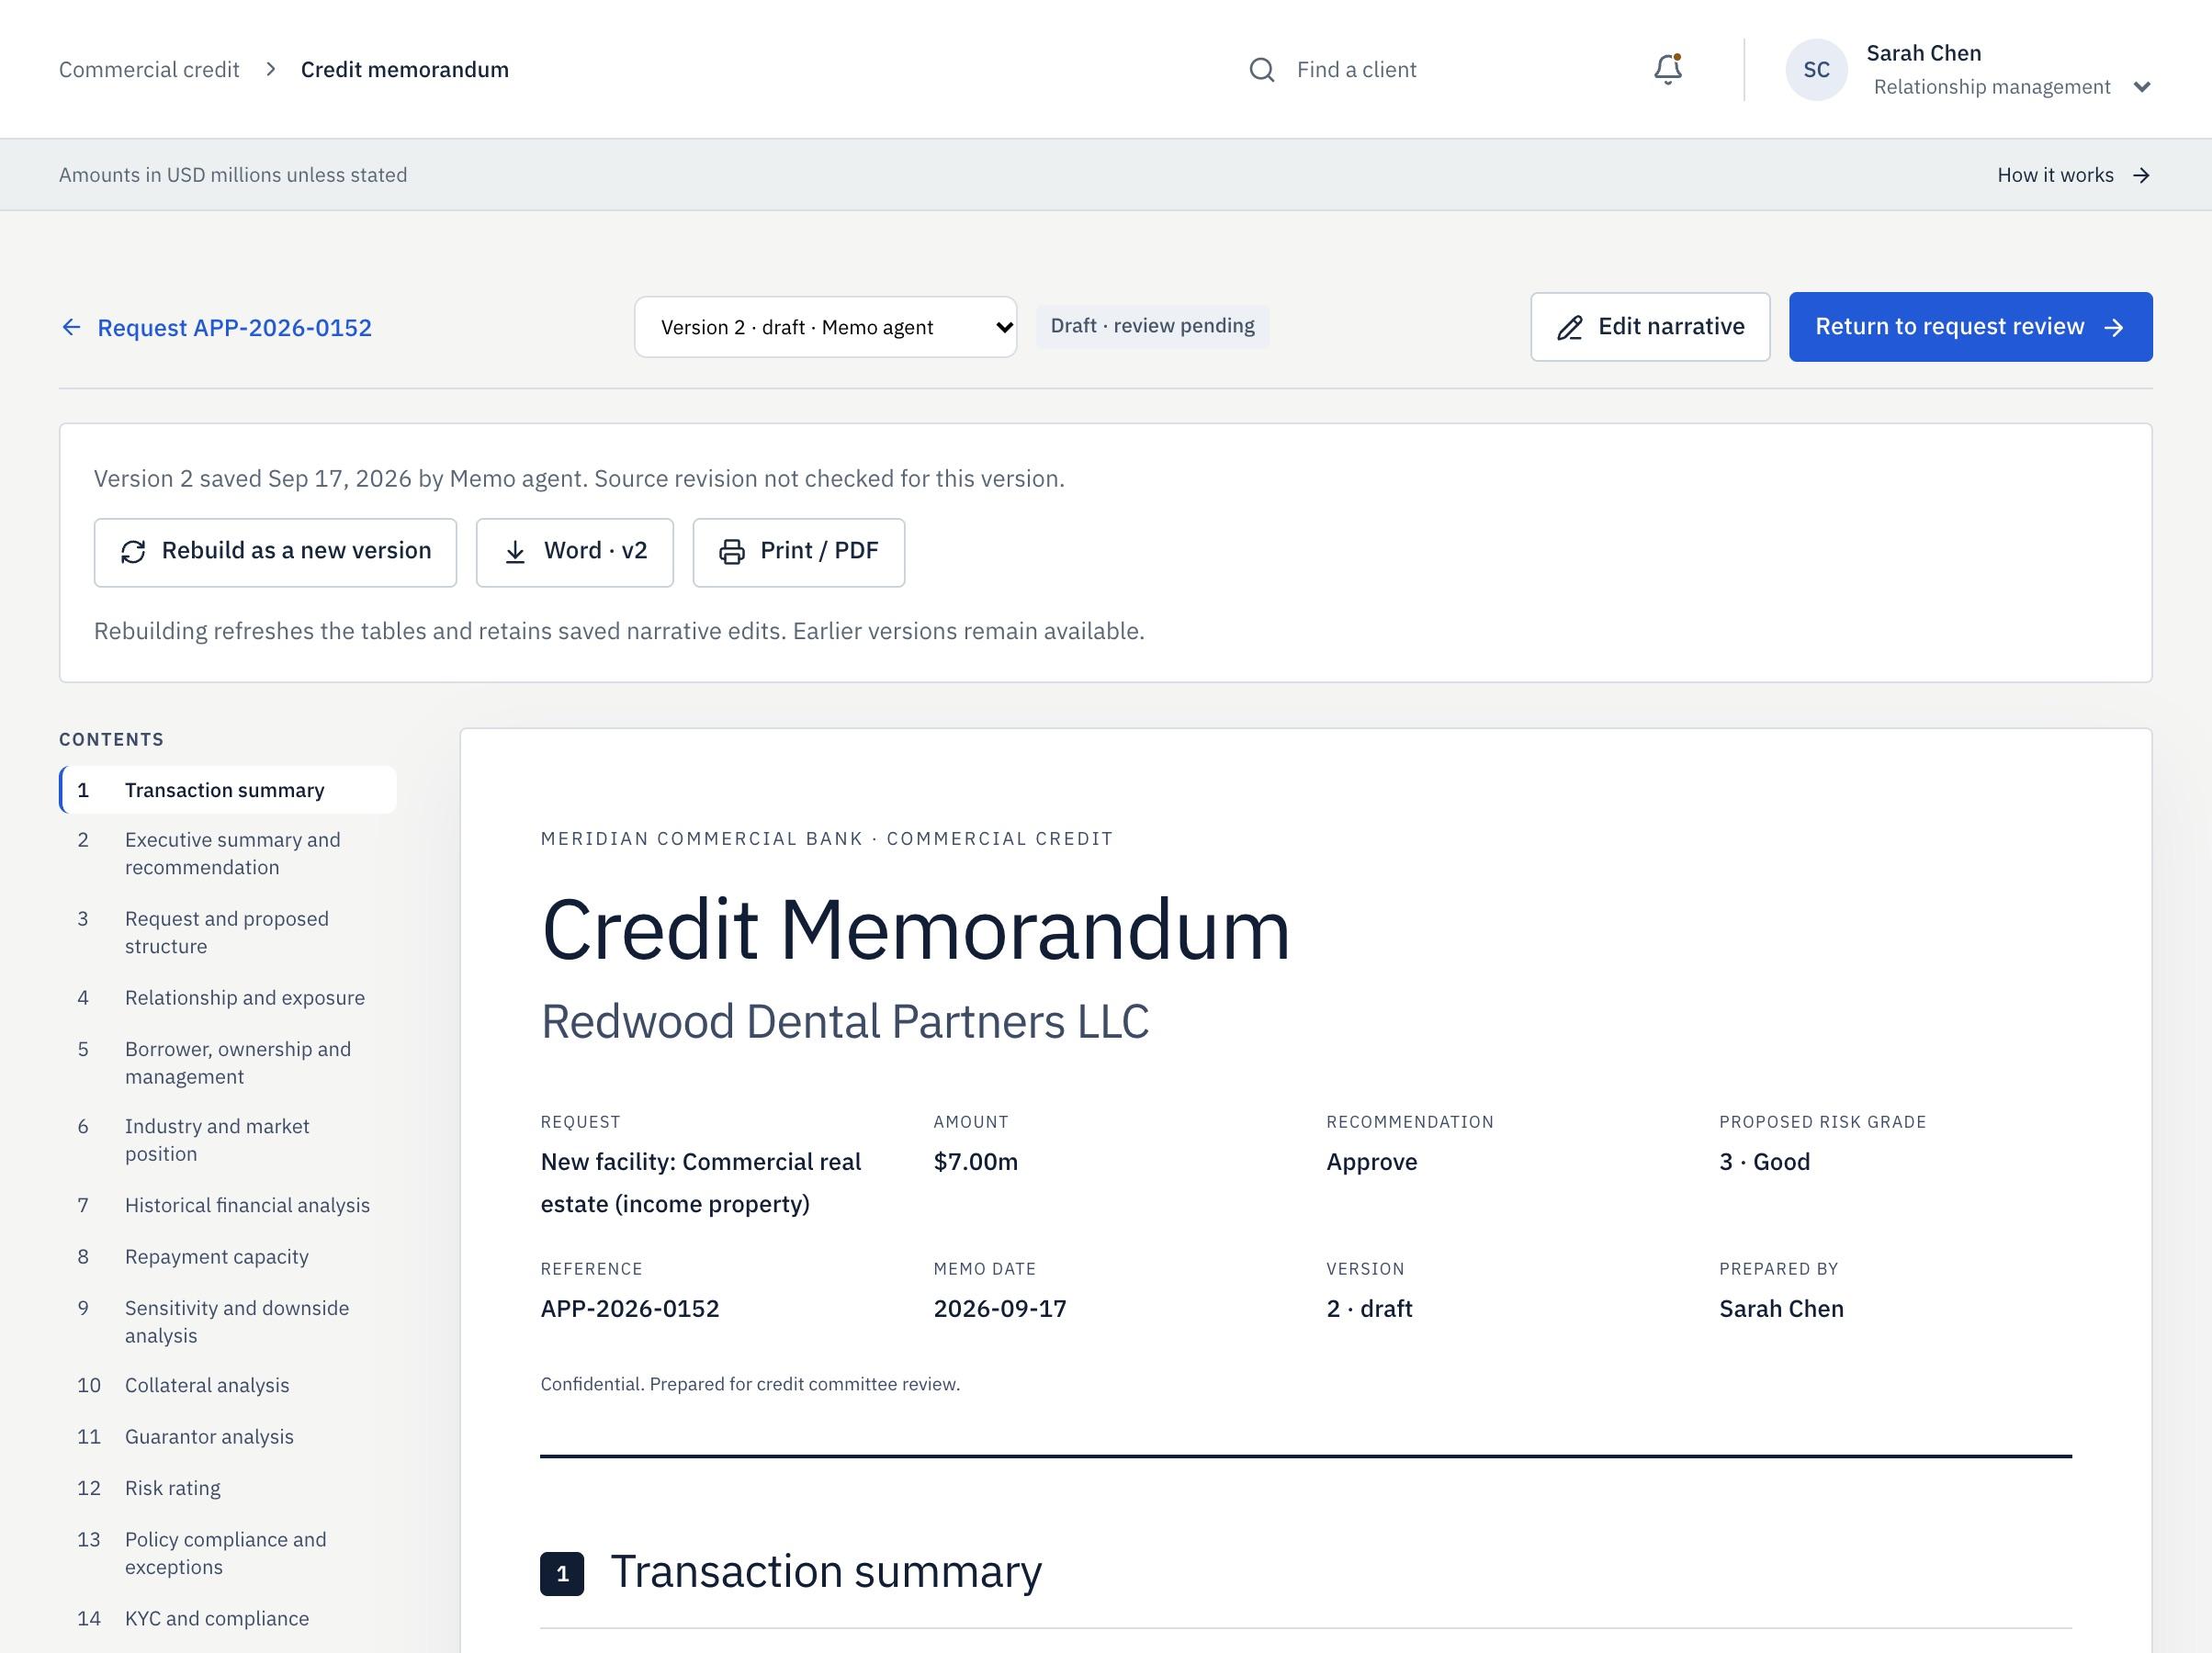
    Credit memorandum drafted for a commercial loan
  4. Wednesday

    The right person decides.

    The approval routes through your delegated authority matrix. If the amount needs the board committee, a credit officer can't sign it alone.
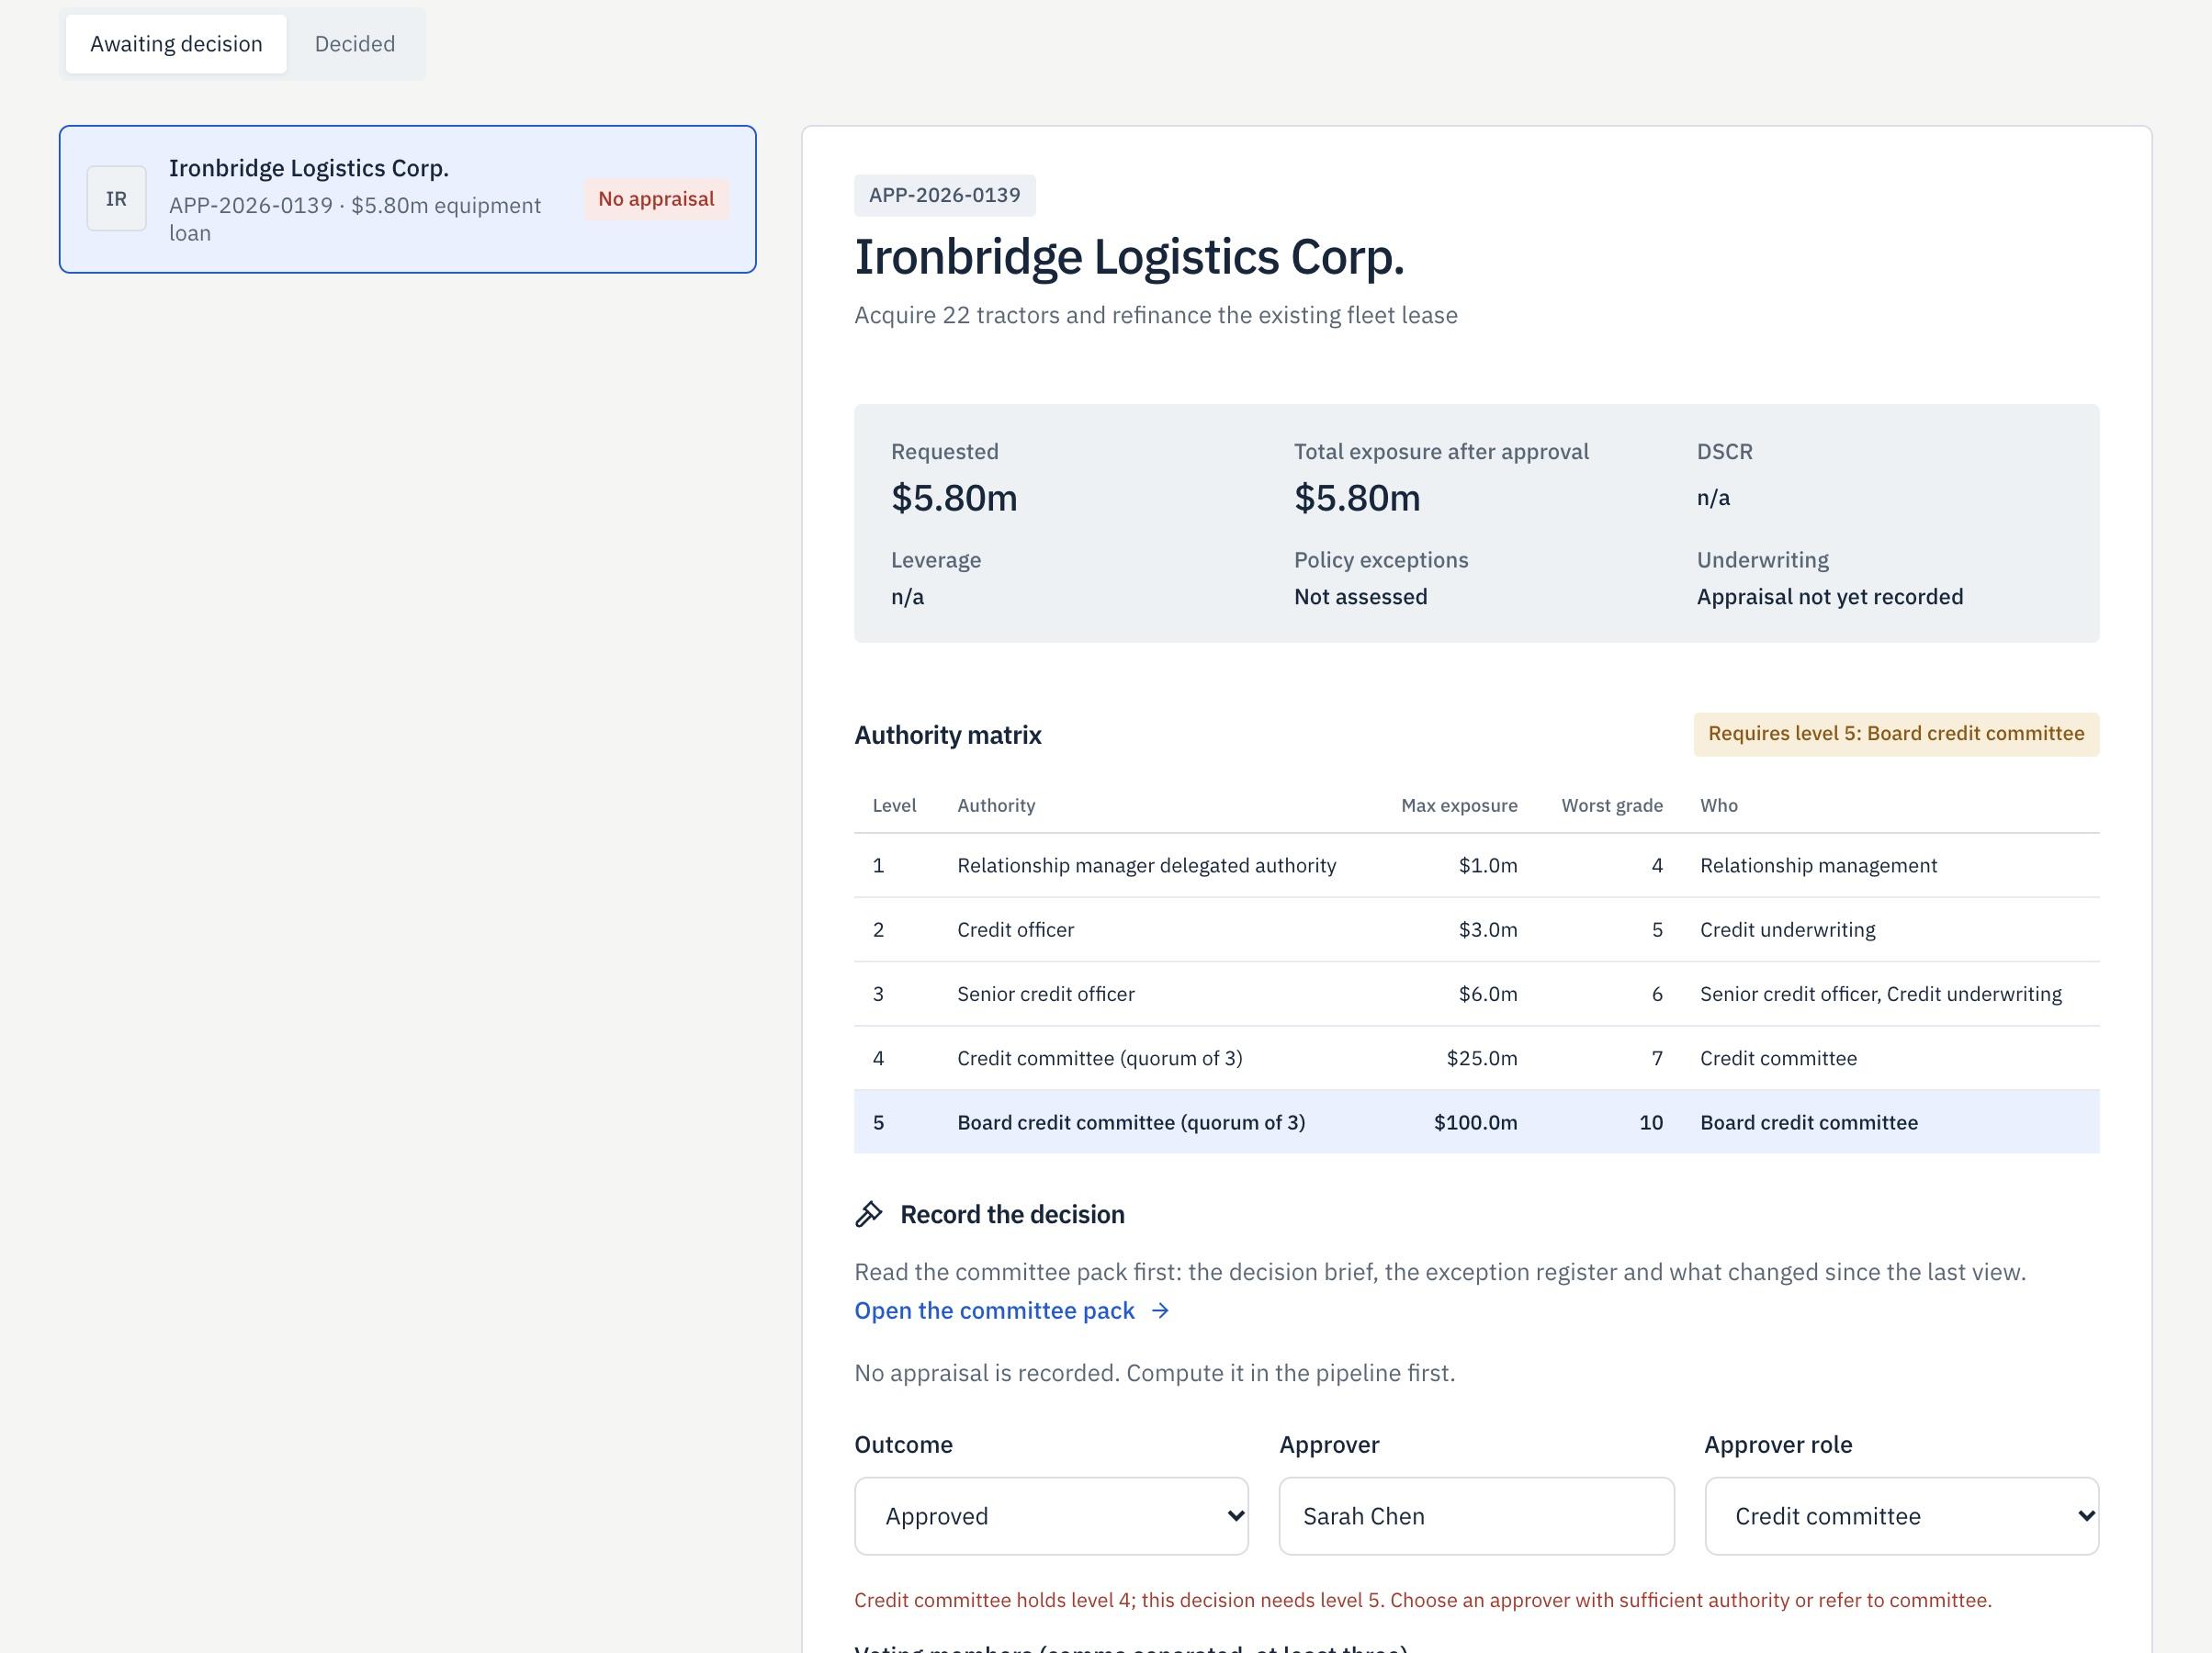
    Authority matrix routing a loan to the board credit committee
  5. Every quarter after

    The loan is watched.

    Covenants are tested as certificates arrive, past-dues surface on their own, and next year's review is drafted before it's due.
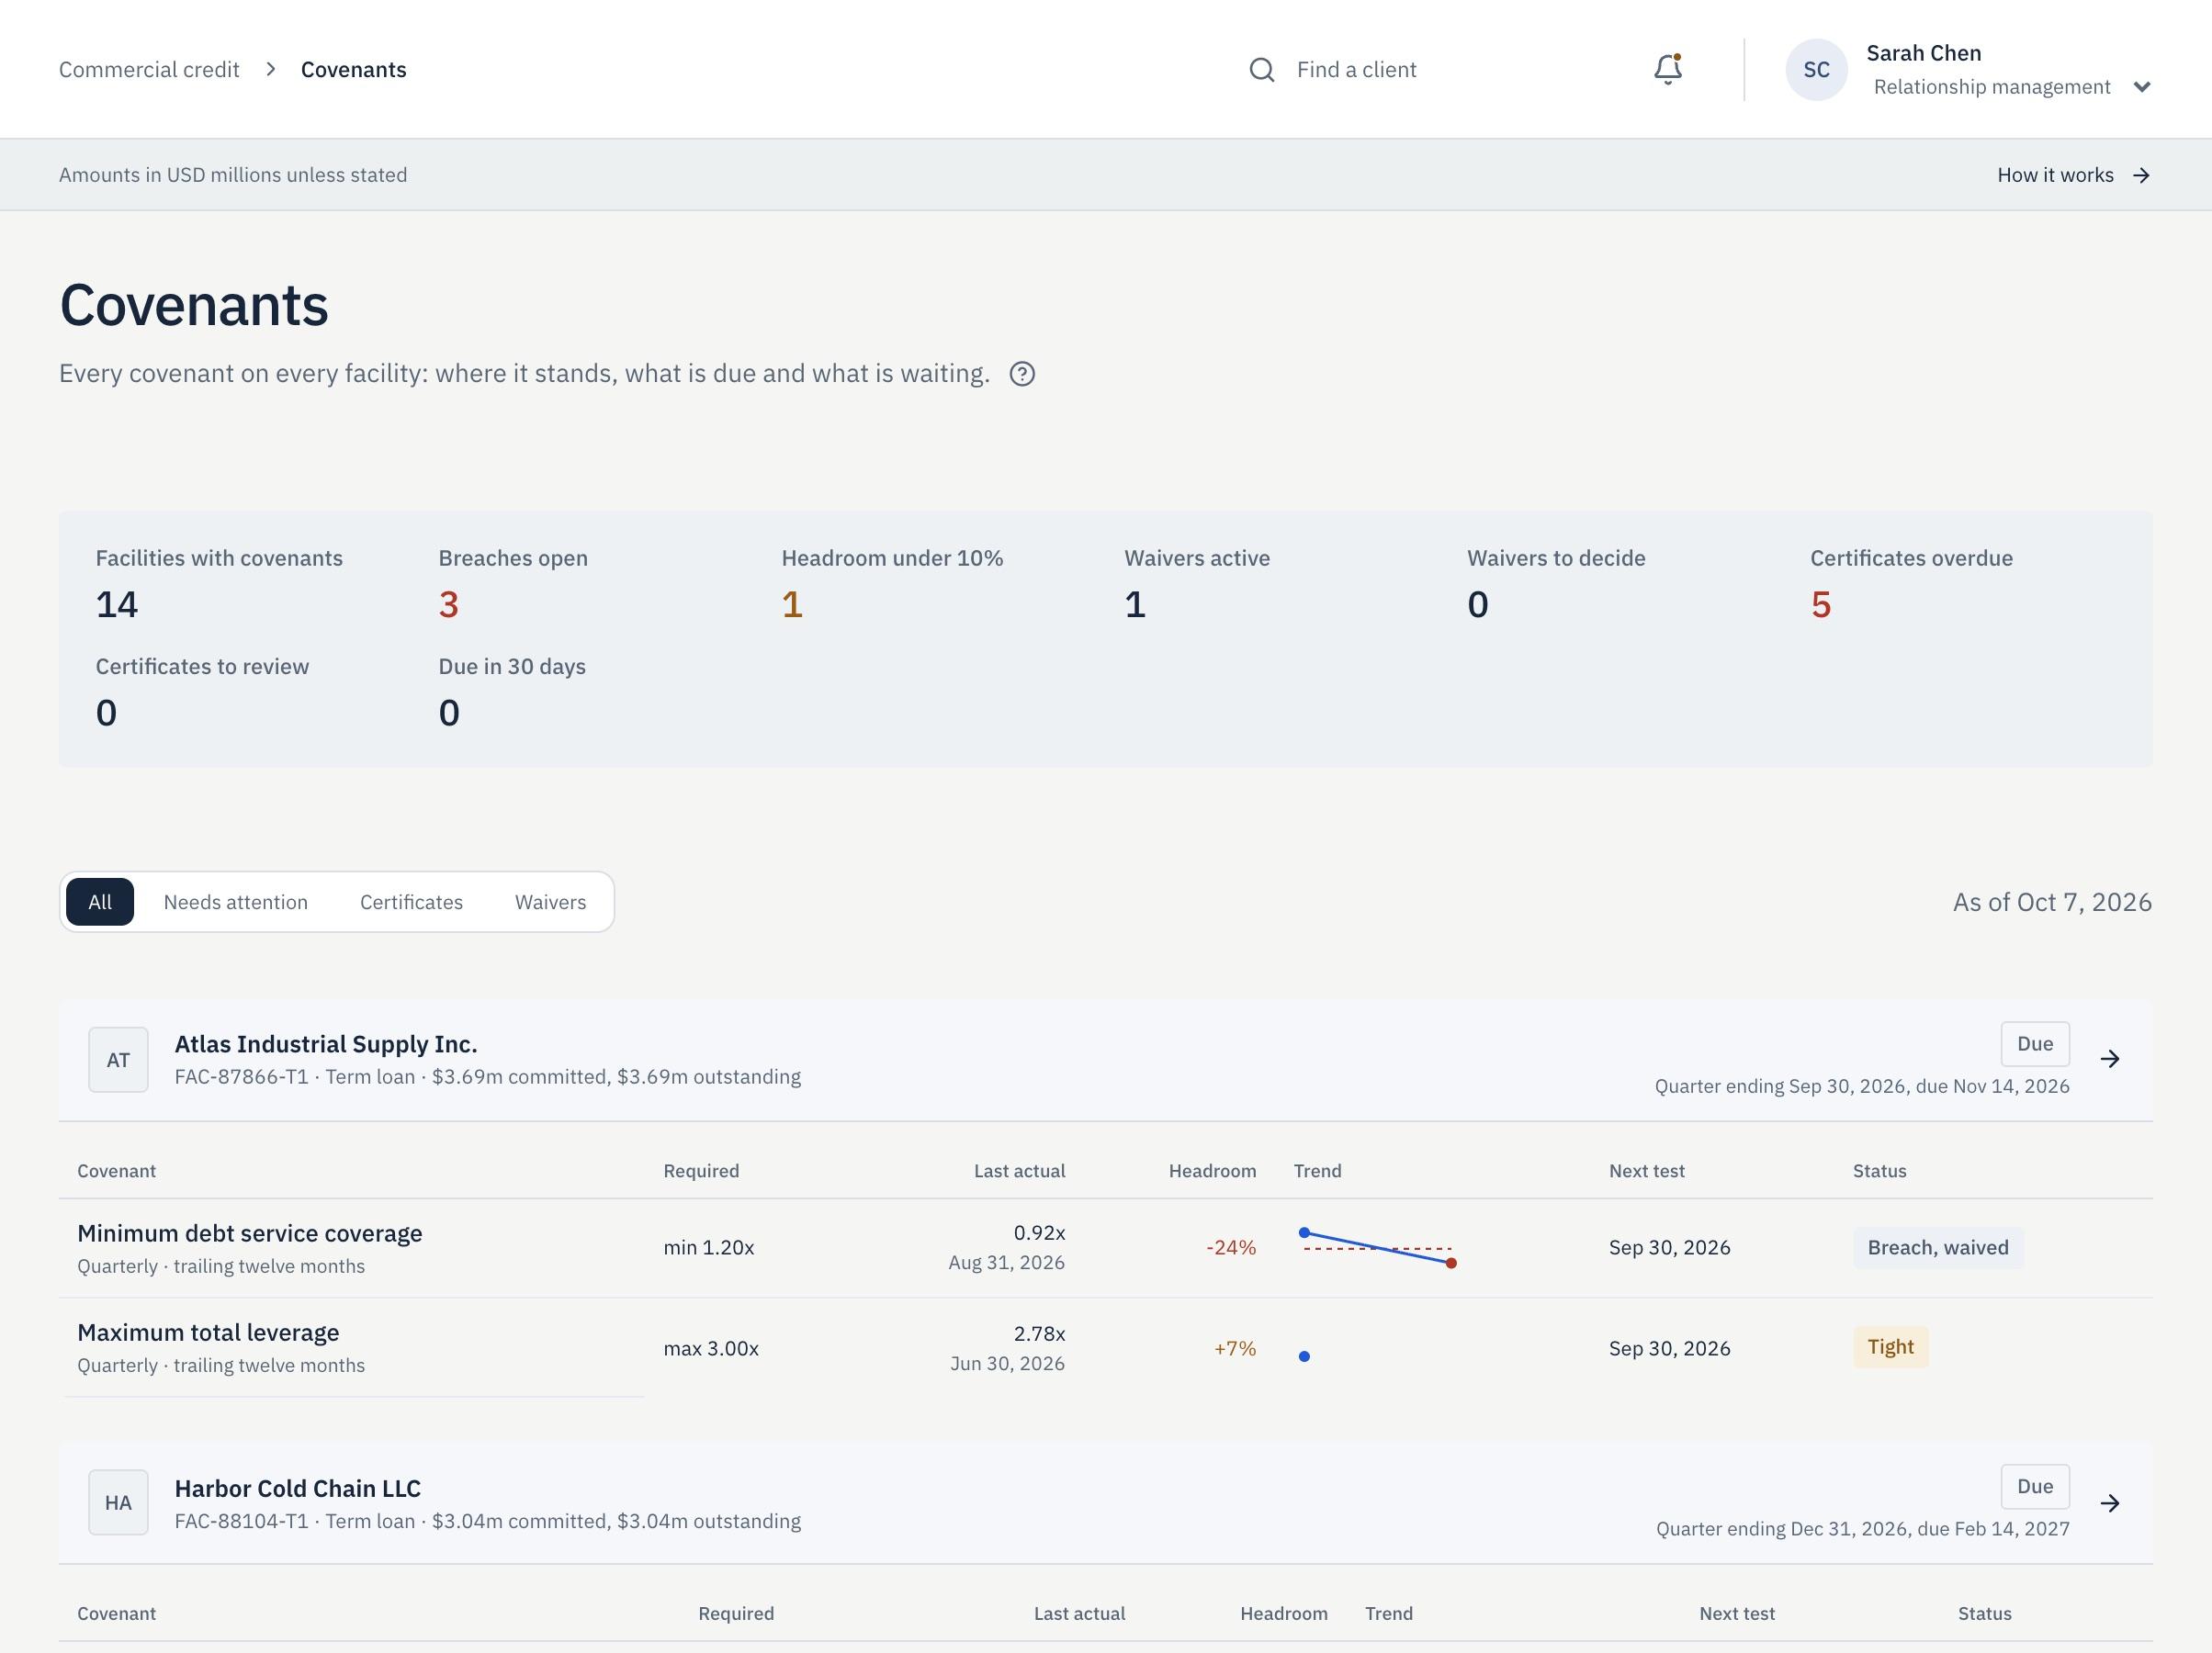
    Covenant register showing breaches and headroom

Everything a commercial credit team does, in one place.

Intake & KYC
Describe the request and point to the documents. The application and checklist build themselves.
Spreading & analysis
Financials spread with page references, policy tests and a debt service schedule, confirmed by an analyst.
Credit memo
Memo and committee pack drafted from the confirmed spread and sources, edited by your credit officer.
Risk grading
A proposed grade kept apart from the grade your reviewer assigns, and flagged when the facts change.
Decision & authority
Every approval routed through your delegated authority matrix.
Closing & booking
Approved, signed and booked terms compared line by line before anything reaches core.
Servicing & covenants
Payments, covenant tests, waivers and certificates, with breaches and past-dues surfaced.
Monitoring & annual reviews
Borrowers ranked by risk signals, with next year's review drafted before it's due.
A hand signing a document with a fountain pen

Your credit policy,
on every step.

Before the AI changes a grade, proposes a line change or touches borrower data, Aarvion checks it against your bank's own rules. Risk signs off on the rules once. Every decision after carries a person's name.

Allow
inside your rules, so it runs
Hold
sent to the right signer, with the reason
Block
outside your rules, so it never runs
Stop all
one switch pauses every AI in the bank
How the controls work

Wednesday, 3:41 pm · Lakeview Hotels

The memo AI proposes moving the grade from BB+ to BB−.

That's two steps. Your policy lets an analyst move one, and the borrower is on the watch list.

HOLDSent to a senior credit officer.
Recorded with the rule that applied, the evidence and who signed. Illustrative example.
A busy production line

Your borrowers keep building.
Keep up with them.
